
College is a good time to start building up your credit. Some landlords take credit scores into account when deciding whether or not to let you rent an apartment, so it’s beneficial to have a good credit history. And if you’re looking to buy a car sometime in the future, having a high credit score can help you secure a low interest rate on a car loan.
Using credit cards, and paying them off in full each month, is a good way to establish your credit. But some college students make financial mistakes that end up hurting their credit scores.
We sometimes hear from students and parents asking if college is even worth attending in today’s era of astronomical costs and a still sluggish-economy. For many, college is a great investment that pays off in the long run by giving students opportunities to enter certain career field and make more money over their lifetimes. But for some people, it’s not worth the cost because they choose the wrong school, never finish their degree, or end up paying too much.
Instead of asking whether college is worth it, Washington Monthly argues that students and families should be asking themselves, “What colleges will charge people like me the least and give me the highest chance of graduating with a degree that means something in the marketplace?” So they created a formula to help college students and families figure it out.

Ever wondered how today’s college graduates (and their student loan debt loads) compare to those of previous generations? This infographic from Manilla explores how tuition, college fees, and student loan debt have skyrocketed since today’s graduates’ grandparents went to school. Even adjusting for inflation, the cost of college, particularly at private universities, has gotten out of […]

In his recent trip to nearby Buffalo, Syracuse, and Binghamton, President Obama revealed his new plan to make college more affordable.
This handy infographic from the White House explains the major reforms and initiatives the President hopes to advance in order to hold colleges accountable for providing a quality education, encourage schools to use technology to cut costs, and make it easier for borrowers to repay their student loans.
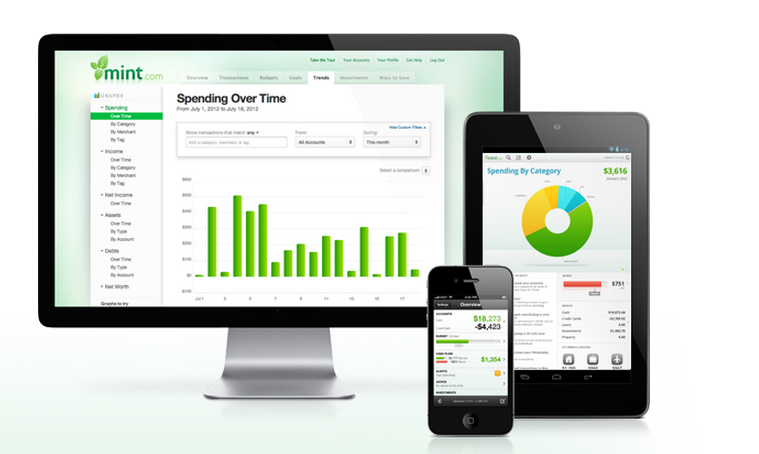
If you’re a college student relying on financial aid, it’s essential to live within your budget while at school. It can be tempting, however, to splurge on expensive dinners out, new clothes, and late night food and drink.
Check out these tips for college students on spending within your means and avoiding the temptation of going into further debt for frivolous expenses.
In his visit to Western New York today, President Obama unveiled a series of higher education reforms aimed at making college more affordable. A new way of ranking colleges His ideas include creating a new rating system for colleges that would judge schools on measures like tuition, graduation rates, debt and earnings of graduates, and […]
The cost of college has risen all over the country, and schools in our home of Western New York have not been an exception.
Check out this video from WGRZ to learn about the cost of higher education in the Western New York region and how President Obama will address the issue in his visit to the area later this week.
On Wednesday, July 31, 2013, the U.S. House gave final passage to a compromised bill for student loan interest rates. The president signed it into law on August 9, 2013.
For new student loans made since July 1, 2013, the new rates for this year will be 3.86% fixed for undergraduate Direct subsidized and unsubsidized loans, 5.41% fixed for Graduate Direct unsubsidized loans and 6.41% fixed for Direct PLUS loans. This is significantly less than borrowers would be paying if a deal hadn’t been brokered.

Learning how to manage your finances early on in college can save you time, stress, and money later. And it’s the best way to prepare for unexpected college costs–such as a once-in-a-lifetime study abroad opportunity or that tropical Spring Break vacation you want to take with your roomies.
On Wednesday, July 31, 2013, the U.S. House of Representatives gave final passage to a compromised bill for student loan interest rates and the president is expected to sign. For new student loans made since July 1, 2013, the new rates for this year will be: 3.86 percent for undergraduate Stafford subsidized and unsubsidized loans […]